✅Retirement Test ✅ https://caniretirenow.org/
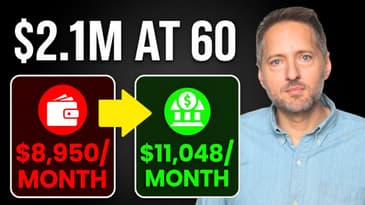
Sam had $2 million saved, a spouse who just got laid off, and a boss pushing AI at work. He was exhausted. He'd run every retirement calculator he could find, and they all said the same thing: not yet.
But here's what those calculators were getting wrong.
Sam was building his plan on three assumptions that made his situation look far worse than it actually was. He was locking himself into a rigid withdrawal rate, modeling his retirement spending as a straight line that just climbs with inflation forever, and leaving zero room for flexibility if markets had a rough stretch.
When we rebuilt his plan with a dynamic income strategy, a realistic retirement spending curve, and a simple mental framework for separating must-haves from nice-to-haves, something shifted.
Suddenly, the $2,000 monthly gap he thought he couldn't close didn't look the same anymore.
In this video, I walk through Sam and Teresa's actual numbers inside our planning software, including what their withdrawal rate looks like in the early years of retirement, how Social Security changes the picture down the road, and what happens to their plan if they had retired into the Great Depression or the stagflation era.
The results surprised him. They might surprise you too.
Chapters
00:00 Introduction
03:22 3 Changes to the Plan
05:15 Looking at the Numbers
10:05 Stress-Testing the Plan
13:11 Variables Left Out
14:04 Conclusion
*Private Facebook Group* // http://facebook.com/groups/retirementforum
--------------------------------------------------------------------------------------------------------------------------------
*ABOUT ME*
I’ve always been passionate about personal finance, investing, real estate, and helping people find the freedom to live their life with purpose. But when my dad died in 2015, I tried to help my Mom find an advisor to sort out her finances. Instead of a helping hand, I found an industry of financial advisors dominated by glorified salespeople working on commission — pushing products that were not in my mother’s best interest. Or advisors with minimums that shut-out all but the ultra wealthy. Disappointed with the options, I took matters into my own hands and launched Foundry Financial, a wealth management firm with transparent pricing that specializes in helping provide clarity around money — so you have the confidence to make smart decisions.My goal is to help a million people retire without worry!
📅 *THE BASICS OF RETIREMENT PLANNING*
Retirement planning has several steps, with the end goal of having enough money to quit working and do whatever you want. Our goal is to help people master retirement and retire without worry.
Step 1: Know when to start retirement planning. When should you start retirement planning? The earlier you start planning, the more time your money has to grow. That said, it’s never too late to start retirement planning. Even if you haven’t so much as considered retirement, don’t feel like your ship has sailed. Every dollar you can save now will be much appreciated later. Strategically investing could mean you won't be playing catch-up for long.
Step 2: Figure out how much money you need to retire, The amount of money you need to retire is a function of your current income and expenses, and how you think those expenses will change in retirement.
Step 3: Prioritize your financial goals. Retirement is probably not your only savings goal. Lots of people have financial goals they feel are more pressing, such as paying down credit card or student loan debt or building up an emergency fund.Generally, you should aim to save for retirement at the same time you're building your emergency fund — especially if you have an employer retirement plan that matches any portion of your contributions.
Step 4: Choose the best retirement plan for youA cornerstone of retirement planning is determining not only how much to save, but also asset allocation. It can make a massive difference in your retirement plan.
Step 5: Select your retirement investments. Retirement accounts provide access to a range of investments, including stocks, bonds and mutual funds. Determining the right mix of investments depends on how long you have until you need the money and how comfortable you are with risk. It’s often helpful to talk with an adviser to discover the right mix of stocks and bonds.
❣ *SPONSORED* To the extent a viewer purchases the third-party software through Kevin Lum’s referral link, he and/or Foundry Financial LLC may receive compensation as a result.
⚠️ "DISCLAIMER:⚠️This is not financial or investment advice. This Channel is meant for EDUCATIONAL AND ENTERTAINMENT PURPOSE only. None of this is meant to be construed as investment advice, it's for entertainment purposes only. #retirementplanning #retirement #passiveincome